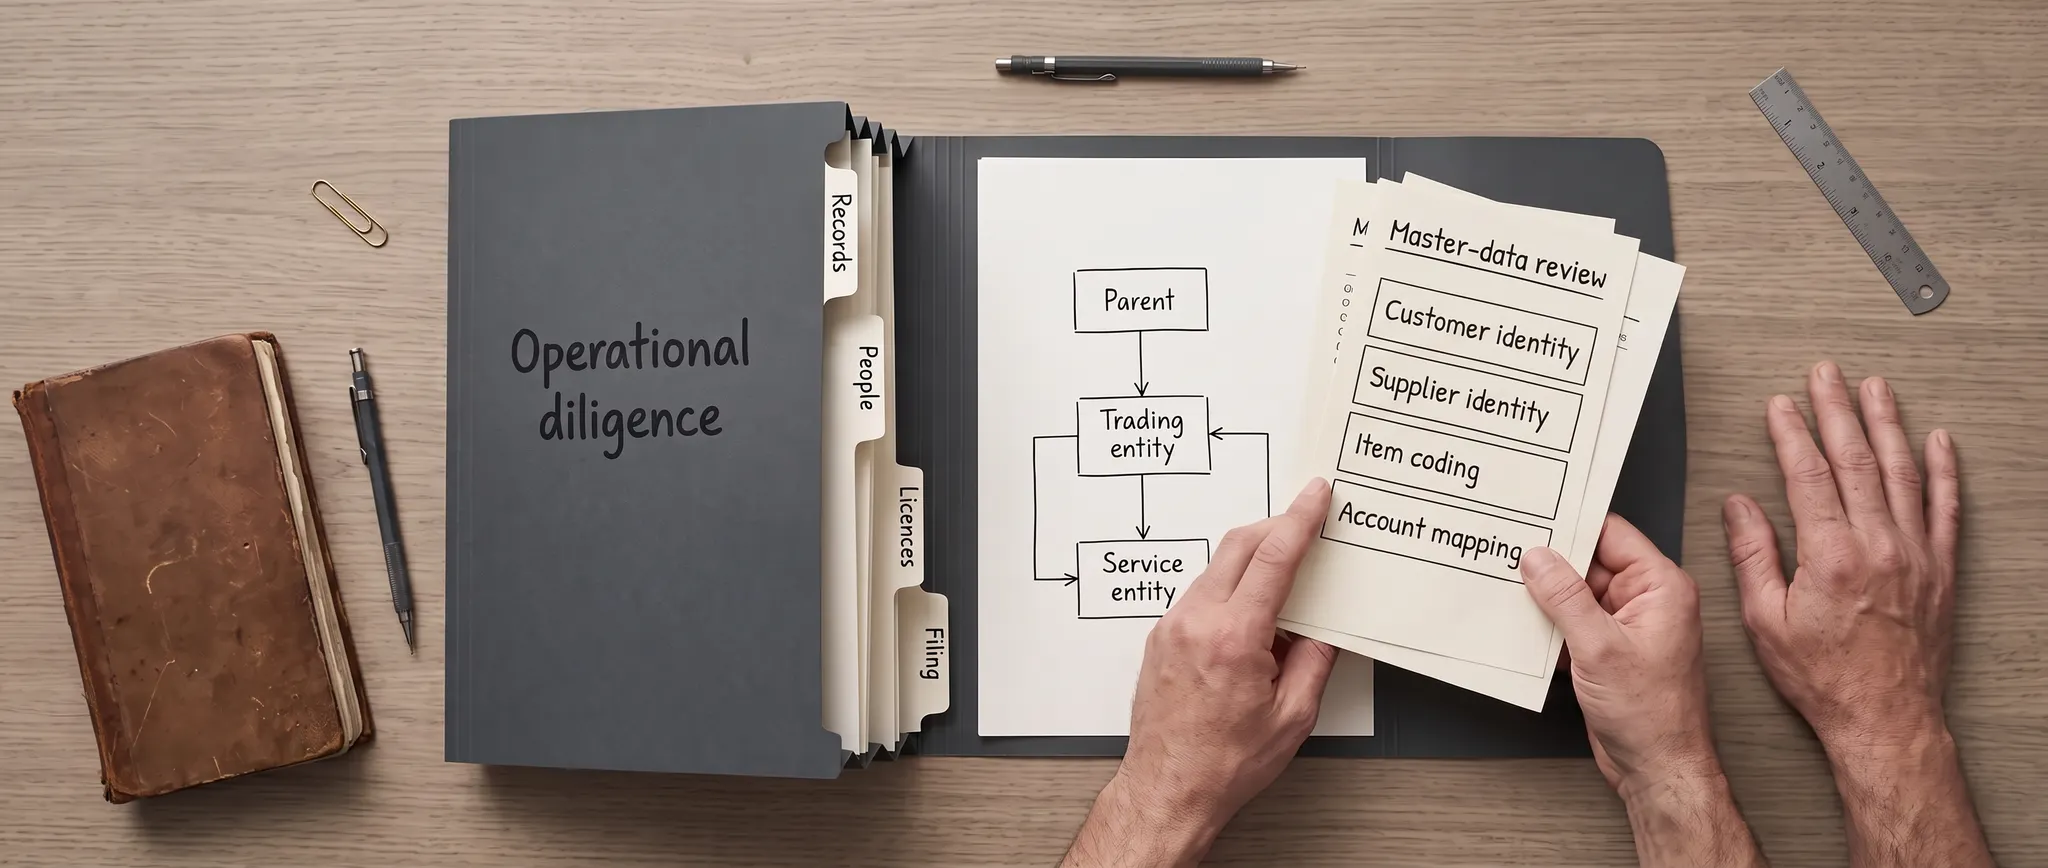
Financial diligence on a roll-up target answers whether the numbers are real. It rarely answers the question that determines whether the deal works, which is what it will cost to run this business inside yours once the founder has gone and the bookkeeper who knew everything has taken the retention bonus and left anyway. That cost is knowable before signing. It is just not in the data room.
Financial diligence tells you what the business earned. Operational diligence tells you what it will cost you to keep earning it, and in a roll-up the second number is the one that compounds
Here is what to examine, and in what order.
The five things that actually determine integration cost
Where the numbers come from. Not the reported figures but the mechanism: which system, how much of it is spreadsheet, who performs the month-end adjustments and whether they are documented. A target reporting cleanly from a manual process is a target whose reporting stops when one person leaves. Master data condition. Customer and supplier records, product and item coding, the chart of accounts. This is the single largest driver of integration effort and the easiest to inspect — ask for an export and look at it rather than asking a question about data quality, which always gets the same answer. Contractual and licensing entanglement. Systems licensed through the seller's group, shared services provided by an affiliate, software contracts with change-of-control clauses. Each one is either a transition services agreement or a surprise. Process concentration. How many critical processes run through one individual. In businesses of the size typically rolled up, the answer is usually two or three people and nobody has written any of it down. Statutory and filing position. Whether returns have been filed correctly, on time and on a basis the acquirer can continue, which is a compliance question with a direct operational cost attached.
The order to do it in
Master data first, because it is fast, cheap and predictive. A two-hour review of an export tells you more about integration cost than a week of management interviews. Then process concentration, because it determines your retention strategy and your timeline, and because it is the finding most likely to change the price. Then contracts and systems, then the statutory position, which is usually the least surprising of the five.
| Area | Evidence to inspect |
|---|---|
| Reporting mechanism | System outputs, manual adjustments and their owners |
| Master data | Customer, supplier, item and account exports |
| Licensing and contracts | Shared-service dependencies and change-of-control terms |
| Process concentration | Critical tasks and the people who can perform them |
| Statutory position | Filing history and the acquirer's continuation basis |
Qualitative summary of this article's source text, not a measured outcome or performance estimate.
What to do with the findings
Price them, do not just note them. Integration cost is a real adjustment to enterprise value, and in a roll-up doing four deals a year it is the difference between accretive and exhausting. Sellers rarely dispute a costed operational finding; they dispute vague concerns about systems.
Practical Guidance for Operational Due Diligence
- Request a master data export before management meetings.
- Map which processes run through one person.
- List every system licensed through the seller's group.
- Check change-of-control clauses in the operational contracts.
- Test how the reported numbers are produced, not just their accuracy.
- Cost each finding and put it in the price.
- Plan retention for the bookkeeper, not only the management team.
- Standardise the diligence pack across deals; roll-ups repeat.
The Regional Angle
The first regional factor is that target companies in the Gulf are frequently structured for licensing reasons rather than commercial ones, and the operational consequence is a set of entities with overlapping activities, separate books and no consistent coding between them. What looks like one acquisition is often three or four sets of records with different practices, and the integration effort scales with the entity count rather than with revenue. Ask for the entity map and the books for each of them early, because the deal model is usually built on consolidated figures that were assembled manually. The second concerns ownership and the informality that goes with it. Owner-managed regional businesses commonly have related-party transactions, personal and corporate expenses that are not cleanly separated, and arrangements with suppliers or landlords that exist on the strength of a relationship rather than a contract. Those arrangements do not transfer, and the operational diligence question is not whether they were proper but which of them the business depends on — a favourable supplier term that rested on the founder's standing is a real cost line the month after completion. The third is about workforce continuity, which is sharper here than in most markets. Key operational staff are frequently expatriates whose residency is sponsored by the target entity, so a change of control can trigger visa transfers, end-of-service settlements and a genuine decision point for each individual about whether to stay. Model the end-of-service liability properly and identify the three or four people whose departure would actually stop the business, because in this region the acquisition itself is the event that prompts them to consider leaving.
The objection worth taking seriously
The strongest objection is one of proportion. Operational diligence of this depth costs money and calendar time, and in a competitive process the buyer who insists on a master data export and a week of process mapping is the buyer who loses the asset to someone willing to move in three weeks on financials alone. Roll-ups succeed on deal flow and pace; a diligence process that adds a month to every transaction reduces the number of transactions, and the arithmetic of the strategy depends on volume. That tension is real, and in genuinely competitive auctions the fast buyer does win. The reconciliation is that most of this is not slow once it is standardised. A master data export takes two hours to review, the process concentration map is one structured conversation, and the systems and contracts list is a data room request. The parts that genuinely take weeks — detailed process documentation, system architecture review — can wait until after signing, because their purpose is planning rather than pricing. What a serial acquirer should build is a fixed operational diligence pack that runs in parallel with financial work and produces a costed number, not a bespoke investigation each time. Buyers who skip it entirely are not moving faster; they are deferring the discovery to the integration, where it costs more and cannot be priced.
Common Questions
What is the most predictive single indicator?
Master data condition. It correlates with almost everything else, and it can be inspected directly rather than asked about.
Should operational findings change the price or the plan?
Both, but the price conversation only happens before signing. Findings that become plans after completion are costs you absorbed.
How much integration cost is typical?
It varies too widely to generalise, which is exactly why it should be estimated per target rather than assumed as a percentage.
What should we expect over the next twelve months?
Expect regional deal volume in the mid-market to stay active, with more first-time institutional buyers of owner-managed businesses. Expect end-of-service and workforce continuity to feature more prominently in negotiations. Expect data quality findings to become a standard price adjustment. And expect the acquirers with a standard diligence pack to compound faster than those improvising per deal.
Operational Due Diligence — we run a fixed pack alongside your financial workstream and give you a costed integration number before you sign.