Every enterprise system can produce a recurring invoice. Copy last month's document, change the date, send it. If that were the whole problem, subscription billing would not be the single most common reason a growing subscription business ends up running its most important numbers in a spreadsheet. The hard part is not the invoice. It is the mid-term change: the customer who adds fourteen seats on the eleventh day of a thirty-day cycle, downgrades two of them at renewal, pauses for August, switches from monthly to annual in the middle of a term, and then asks for the whole arrangement to be moved to a different legal entity in another country. Each of those is a separate decision about proration, credit, entitlement and revenue, and a traditional order-to-cash design has nowhere to put any of it.
An order is an event; a subscription is a state
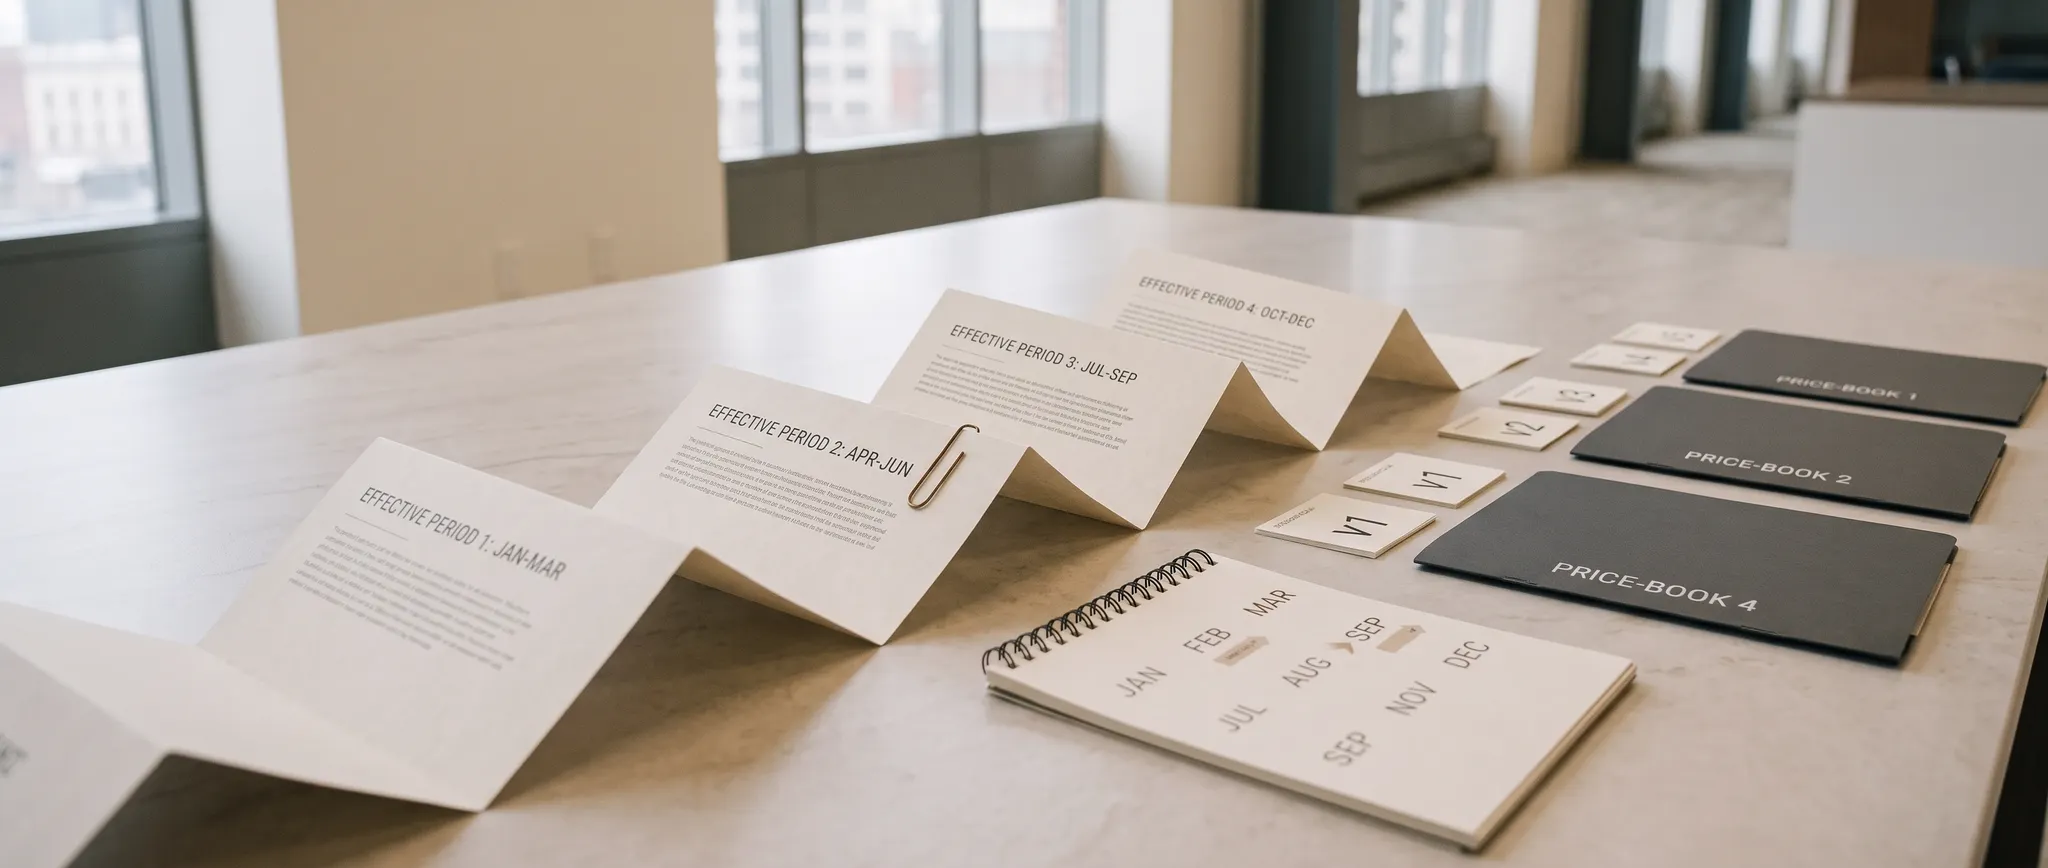
This is the architectural mismatch underneath every failed billing implementation. A sales order records that a quantity was sold at a price on a date. It is a fact about a moment. Subscription commerce needs the opposite: a record of what the customer is entitled to, over which periods, at which price, with a complete history of how that entitlement changed and when. Four objects are required and standard order processing has none of them properly: An entitlement with validity periods. Three seats from the first of January, eleven from the fourteenth of February, cancelled at the end of June. One row cannot express that; a versioned record with effective dates can. A versioned price book. The price the customer is on, not the price you sell today. Grandfathering is not an exception to be handled manually; it is the normal condition of any business more than two years old. A usage meter, where pricing depends on consumption, with the raw events retained long enough to answer a dispute. An event log. Every change, who made it, when it takes effect, and what it did to the amount payable. Without this, the finance team reconstructs history from invoices, which is archaeology rather than accounting.
| Object | What it must preserve |
|---|---|
| Entitlement | The service or seats, validity periods and history of effective changes |
| Versioned price book | The customer's contracted price, including grandfathered pricing |
| Usage meter | Consumption events and detail needed to explain a charge or dispute |
| Event log | Who changed the arrangement, when it takes effect and the effect on the amount payable |
Qualitative summary of this article's source text, not a measured outcome or performance estimate.
The proration policy you have never written down
Here is a test. Ask your commercial and finance leads, separately, what happens when a customer adds users halfway through a monthly cycle. You will get at least two answers, and the system will be doing a third thing. The decisions that need to be made explicitly, before anybody configures anything: Whether proration is calculated daily or by whole months. When a change takes effect — immediately, at the next cycle, or at the contract anniversary. Whether an increase is invoiced immediately or added to the next invoice. Whether a decrease produces a refund, a credit note, or nothing until renewal. What happens to a minimum commitment when the customer drops below it. How a mid-term upgrade interacts with an annual prepayment. And whether a pause suspends the term or extends it. That is nine decisions, each with two or three defensible answers, and the combination defines your billing behaviour more completely than any software selection. Write them on one page and get both functions to sign it. Every system will encode a default for each of these, and if you have not decided, the default becomes policy by accident and someone spends the next two years explaining variances that are really undocumented rules.
Usage pricing is a data problem wearing a billing costume
Where pricing depends on consumption, the difficulty moves upstream. Metering means capturing events reliably from a production system that was not built to be an accounting source, then rating them into charges. Three properties matter and are usually discovered late. Rating must be idempotent, so replaying a batch does not double-bill. It must tolerate late-arriving events, because some will land after the period closes, which forces a decision about whether to restate the period or carry the adjustment forward. And the event detail must be retained for as long as a customer might dispute it — which introduces a retention obligation, and, where the events describe identifiable end users, a privacy obligation that nobody assigned to the billing project. The practical rule: close the meter on a fixed cut-off, publish the usage detail to the customer alongside the invoice, and handle late events as next-period adjustments rather than reopening a closed period.
What this does to revenue and to your metrics
Two downstream consequences deserve naming, briefly. Revenue recognition under the current standards treats a mid-term change as a contract modification, and the accounting treatment depends on whether the change adds distinct services at standalone prices or alters the existing arrangement. That determination is driven entirely by data your billing layer either holds or does not. Where entitlement history exists, recognition is a calculation. Where it does not, quarter end becomes a reconstruction exercise with an auditor watching. The second is metric integrity, which causes more board-level friction than the accounting does. Recurring revenue should be defined on entitlement — what the customer is contracted to pay for the current period — not on invoices issued and not on cash collected. Annual prepayments, credits, pauses and usage overages make those three numbers permanently different. Pick one definition, document it, and make the billing system its source, or you will have three numbers in three decks and an argument every quarter about which is real.
Practical Guidance for Subscription Billing Assessment
- Write the nine proration and effective-date rules on one page and have finance and sales sign it. This costs an afternoon and prevents two years of reconciliation.
- Model entitlement as a versioned record with validity dates, not as an order quantity. If your system cannot express "three, then eleven, then cancelled", nothing downstream will work.
- Keep versioned price books and treat grandfathering as normal. Migrating customers onto current pricing is a commercial campaign, not a data cleanup.
- Define recurring revenue once, on entitlement, and publish the definition. Reconcile it to billed and collected monthly rather than arguing about which is correct.
- Draw the boundary deliberately: billing owns entitlement and rating; the ERP owns tax, receivables, the ledger and revenue. Duplicated ownership of any of those four is where estates rot.
- Decide the tax point for every billing pattern before go-live, especially annual invoices in advance, and check it against local rules rather than the vendor's default.
- Design collections for the payment instruments your customers actually use. Automated card collection is an assumption, not a fact, in much of the world.
- Retain usage events for the full dispute window, and name an owner for that data. It is both an audit record and, often, personal data.
The Regional Angle
Three regional specifics change the design, and the first one costs real money. The tax point does not wait for your revenue. Under the value added tax regimes now operating in this region, the obligation on a supply generally crystallises at the earlier of the invoice being issued or payment being received, with particular rules for continuous supplies and periodic payments. A subscription business that invoices twelve months in advance is therefore accounting for output tax on the whole amount in the current return period, while recognising the revenue over the following twelve months and, quite possibly, collecting the cash in instalments. The accounting is correct and the cash flow is unpleasant, and it is routinely discovered in the first quarter after a pricing change. Model the tax cash profile of every billing pattern before you offer it, and be particularly careful with annual prepayment discounts, which can be margin-positive and cash-negative at the same time. Place of supply decides the rate, and your contracting entity decides place of supply. A regional group selling the same subscription from a mainland entity, a free-zone entity and a foreign entity may be looking at standard-rated, zero-rated or out-of-scope treatment for identical services, depending on where the customer is established, whether the customer is registered, and which of your entities signed. Since the rate now differs materially between Gulf states, the billing system needs the customer's tax status and place of establishment as structured data — not as a note in the account record — and a rule that maps entity plus customer status plus service type to a rate. Retrofitting that after a year of invoices is a voluntary disclosure exercise. Credit notes are becoming regulated documents. With electronic invoicing requirements now published in Saudi Arabia and a clear direction of travel across the region, the proration credit note stops being an internal adjustment and becomes a structured document that must reference the original invoice and carry prescribed content. Any billing design that handles downgrades by quietly netting them into the next invoice is going to need rework. Build the credit note properly now: one document per adjustment, with a reference to what it adjusts. A fourth point, briefly: automated collection cannot be assumed here. Business-to-business subscriptions in this market are frequently settled by transfer or instrument rather than by a stored card with a mandate, which means involuntary churn from a failed card is a smaller problem than in mature subscription markets and collections labour is a much larger one. Dunning is a person with a telephone, and the system's job is to give that person an accurate ageing by entitlement rather than to retry a payment method that does not exist.
The objection worth taking seriously
The honest objection is that most of this is premature. A business with two hundred customers on annual contracts does not need a rating engine, an event log and a versioned price book. It needs a competent accountant, a well-maintained spreadsheet and an ERP that produces an invoice. Buying specialist billing infrastructure at that scale adds an integration to maintain, a second source of truth to reconcile, and a licence cost that buys capability the company will not use for three years. Plenty of subscription businesses have reached serious revenue on exactly that stack. That is right, and the usual advice — buy the platform early — is mostly vendor interest speaking. The better threshold is not customer count but change rate. Five thousand identical annual subscriptions that never change mid-term are administratively trivial. Three hundred contracts with weekly seat adjustments, three pricing generations, a usage component and two contracting entities are not, and no spreadsheet survives that for long. The measure to watch is the number of mid-term contract changes per month and the proportion of invoices that require a manual adjustment. When either starts growing faster than your customer count, the model has outgrown the tooling. And the first response is still not a purchase. It is the one-page policy, because a business that cannot state its own proration rules will implement the same confusion on better software.
Common Questions
Should billing live inside the ERP or alongside it?
Either can work. What matters is that entitlement and rating have exactly one owner, and that tax, receivables and the ledger stay with the system of record. The failures come from splitting a single responsibility across two systems, not from having two systems.
How should we handle customers on old pricing?
As a normal state, with a versioned price book, and as a commercial project when you want to move them. Never by editing historical prices, which destroys the ability to explain any past invoice.
What breaks first as a subscription business scales?
Proration and credits, closely followed by the recurring revenue number. Both fail for the same reason: the entitlement history was never stored, so every question requires reconstruction.
What should we expect over the next twelve months?
Expect consumption-based pricing to spread well beyond software — industrial equipment, medical devices and logistics services are all being repackaged as subscriptions and managed services this year, and each of those brings metering into companies with no billing engineering at all. Expect electronic invoicing mandates in this region to formalise credit and debit notes, which will force billing rework at exactly the companies that treated adjustments informally. Expect auditors to ask sharper questions about contract modification accounting, now that the standards have been in force long enough for the easy year to be over. And expect at least one board conversation in which three recurring revenue figures appear on the same slide, which is the moment most organisations finally define the metric.
Subscription Billing Assessment — we document your proration and effective-date rules, model the tax and cash profile of each billing pattern, and draw the boundary between billing and the ledger before the reconciliation becomes someone's full-time job.