For twenty years, buying outsourced back office work meant buying people. So many full-time equivalents at so much per month, in a location chosen for its labour cost, with a management layer priced on top. That model is breaking, and the reason is simple arithmetic: once a provider automates a process, selling you the hours it no longer needs stops being defensible. Subscription models hit BPO because the labour unit stopped describing what is actually being delivered. What replaces it is more varied than the word subscription suggests, and the difference between the variants is where all the money is.
Four pricing models, and what each one rewards
Per head. You pay for capacity. The provider carries no volume risk and has no financial reason to make the process faster, because efficiency reduces its revenue. Every productivity conversation becomes an argument about whether to release a headcount you are already paying for. Per transaction. You pay per invoice processed, per employee paid, per case resolved. Costs now move with your business, which is what most buyers say they want, and the provider finally has an incentive to automate because savings accrue to it. The risk moves to definition: what exactly is a transaction, and who decides. Subscription tiers. A fixed monthly fee for a service within a volume band, with defined step-ups. Predictable for budgeting, simple to administer, and it works well where volumes are stable. It fails where volumes are lumpy, because you pay for the band rather than the use. Outcome-based. Payment tied to a result, days sales outstanding, close cycle length, error rate, first-time-right percentage. Theoretically the best alignment and practically the hardest to run, because outcomes depend on things the provider does not control, and the measurement argument tends to consume the relationship. Most sensible contracts now blend these: a subscription base covering the service, transaction pricing above a band, and a small outcome component on two or three measures that both sides accept are attributable.
| Pricing model | Definition to settle |
|---|---|
| Per head | Which capacity and retained responsibilities are included. |
| Per transaction | What counts as a unit and how exceptions and rework are treated. |
| Subscription tier | How volume bands and changes apply in both directions. |
| Outcome | Which result is attributable and how it is verified. |
Qualitative summary of this article's source text, not a measured outcome or performance estimate.
The definition work nobody enjoys
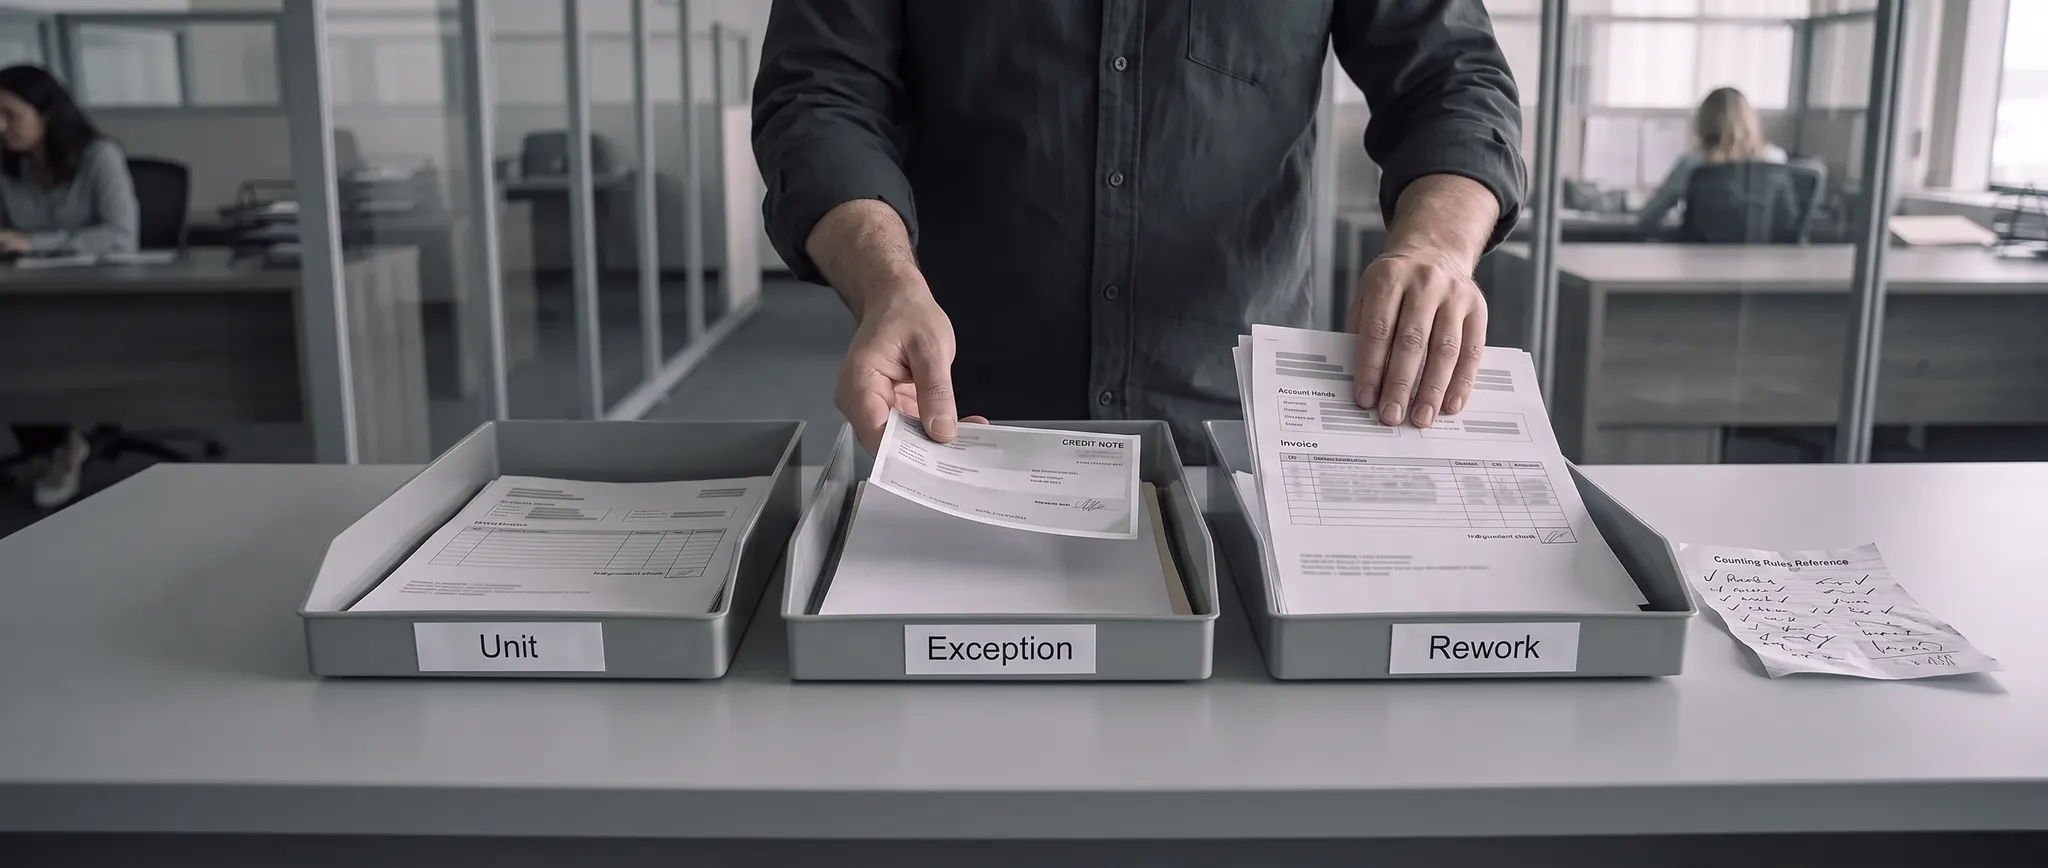
Moving off headcount pricing shifts the negotiation from rate cards to definitions, and this is where deals are won or lost. What counts as a unit has to be written down with edge cases resolved in advance. Is a credit note a transaction. Is a multi-line invoice one unit or five. Is a rejected item that returns corrected a new unit or the same one. Does a payroll run for fifteen leavers cost the same per head as fifteen ordinary employees. Every one of these becomes an invoice dispute if left to good faith. Baseline volumes and bands need to come from your actual data rather than the provider's estimate, including seasonality. Back office volumes are never flat; they spike at month end, quarter end and year end, and a band set on an annual average will be breached every quarter. Exceptions need their own treatment, because exception handling is where the real effort lives. A process that is ninety per cent straight-through and ten per cent exceptions will have most of its cost in that ten per cent, and a provider that has priced the average will either lose money or start classifying aggressively. And the price has to step both ways. Volume bands that increase the fee when you grow but never decrease it when you shrink are extremely common and rarely noticed until a downturn.
The automation ownership question
Here is the item that belongs at the top of any transition plan and usually appears nowhere. When a provider automates part of your process during the contract, who owns the automation, and who gets the benefit. The standard answer, buried in the schedules, is that the provider owns everything it builds and keeps the productivity. You continue paying the agreed unit price while the effort behind it falls, which is a perfectly reasonable commercial outcome for them and the reason the industry is moving to these models at all. The negotiable positions are: a productivity commitment that reduces unit prices on a defined schedule regardless of how the saving is achieved; a share of documented automation benefit; ownership or a perpetual licence for automation built specifically for your processes; and, at minimum, documentation of what has been automated so you are not left with an undocumented black box when the contract ends. Pick at least one. Signing none of them means you have converted a labour arbitrage relationship into a software rental at labour prices.
Practical Guidance for Managed Services Transition Planning
- Measure your real volumes for twelve months before negotiating. By month, with peaks and exception rates. Without this you are accepting the provider's estimate of your own business.
- Define the unit exhaustively, with worked examples. Attach twenty real cases to the contract showing how each is counted. It feels pedantic and it prevents the first year's disputes.
- Price the exceptions separately. Distinguish straight-through from exception handling and agree what happens when the exception rate exceeds the assumption.
- Make the bands symmetrical. If volume growth raises the fee, volume decline must lower it, on the same increments and the same notice.
- Settle automation ownership and productivity sharing before signature. Unit price reductions on a schedule are the simplest mechanism and the easiest to administer.
- Keep process knowledge in your organisation. Documented procedures, current process maps and at least one retained person who understands the end-to-end flow. Otherwise you cannot re-tender, and the provider knows it.
- Write the exit before you need it. Data extraction in an agreed format, transition assistance at agreed rates, a defined period of parallel running, and no dependency on the provider's own tooling.
- Agree the quality regime alongside the price. Accuracy, timeliness and rework are what a low unit price is bought with, and they need service levels with consequences rather than reporting.
The Regional Angle
The Gulf adopts these models more slowly than the global market, and the obstacles are structural rather than cultural. The largest is procurement format. A great deal of regional buying, particularly by government-related entities, large contractors and family conglomerates, runs through tender templates that require priced line items against defined resources: names, grades, day rates, headcount. A subscription or per-transaction proposal does not fit the evaluation sheet, and bids that do not fit the sheet get marked down or disqualified. Buyers who genuinely want outcome pricing have to change the tender documents first, and that is a procurement project rather than a sourcing one. It is entirely doable and it has to happen before the market can respond. The second is that headcount here is not just a pricing unit; it is a visa, a desk and a residency status. Onshore delivery means people sponsored by someone, and when a provider's staff sit in your offices using your systems under your supervision, you are closer to labour supply than to outsourcing. That distinction matters for regulatory compliance, for end-of-service liabilities and for the wage protection obligations that apply to sponsored workers. It also quietly undermines transaction pricing, because a contract theoretically priced per unit while eight identifiable people sit on your floor every day will be managed, and disputed, as a headcount arrangement. If you want unit pricing, move the work off your premises. Third, the statutory and language dimension of regional back office work resists neat unit definition. Arabic-language documentation, government portal submissions, bilingual invoices, attestation chains and entity-specific filings vary enormously in effort between two items that look identical on a transaction count. Providers price that uncertainty as a risk premium, which is why regional unit prices often look expensive relative to the equivalent in a large offshore market. The answer is not to argue the premium down but to separate those activities into their own pricing category rather than averaging them into the volume. Finally, scale. Transaction and subscription pricing rewards volume, and a single mid-sized regional entity rarely has enough. Groups that consolidate volumes across entities into one arrangement reach the bands that make these models worthwhile, which is an argument for a group-level sourcing decision rather than eight entity-level ones, provided the intercompany recharge and tax positions are worked out in advance.
The objection worth taking seriously
The objection from experienced sourcing people is that subscription pricing buys predictability by surrendering visibility. Under a headcount contract you know precisely what you are paying for and can see whether the team is busy. Under a subscription you receive an invoice for a service, the effort behind it is deliberately opaque, and the provider has every incentive to reduce that effort while the price stays where it is. Buyers do not get the automation dividend; providers do, which is exactly why providers are enthusiastic about the change. The second objection is about risk pricing. Any provider taking on volume risk adds a premium for it, and that premium is usually larger than the variability it protects against, because the provider knows your volumes less well than you do. Organisations with stable workloads frequently pay more under a variable model than they would have under a fixed one, and they pay it every month, quietly. The third is disputes. Outcome-based pricing sounds disciplined and in practice creates an arbitration surface. Days sales outstanding depends on your customers and your sales terms. Close cycle time depends on your controllers. When the measure misses, the argument about whose fault it was consumes more management attention than the saving was worth. All three are sound, and together they define the correct posture rather than a reason to stay with headcount pricing. Keep variable pricing for genuinely variable work and fixed pricing for stable work; do not buy volume protection you do not need. Recover the automation dividend contractually, through scheduled unit price reductions, rather than hoping for goodwill. And limit outcome components to two or three measures that the provider demonstrably controls, with everything else on service levels. What makes staying with headcount pricing untenable is not that it is unfashionable but that it pays a provider to keep your process exactly as inefficient as it is today, and no amount of governance overcomes an incentive that clear.
Common Questions
Is transaction pricing always cheaper?
No. It is cheaper when volumes fall and more expensive when they rise, and it carries a risk premium. Run your last three years of actual volumes through both models before deciding.
What if our volumes are unpredictable?
Then variable pricing is genuinely worth paying for, which is precisely the case where the premium earns its place. Set the bands from real data and make the steps symmetrical.
Should we insist on owning the automation?
Ownership is often unrealistic for platform tooling the provider uses across clients. A scheduled productivity reduction in unit prices achieves most of the benefit with far less negotiation, and documentation of what has been automated protects your exit.
What should we expect over the next twelve months?
Expect the larger global providers to push hard on subscription and outcome pricing, because automation makes headcount pricing indefensible for them too. Expect regional procurement templates to lag by a year or two, which will keep headcount contracts dominant here even as the pricing conversation changes. And expect the first regional disputes over unit definitions and automation benefit to make the definitional work in this article look considerably less pedantic than it does today.
Managed Services Transition Planning — we measure what your processes actually consume, define the units before the provider does, and make sure the automation dividend reaches your side of the contract.